Ocean View Isn't Enough for a Flagler Beach Second Home
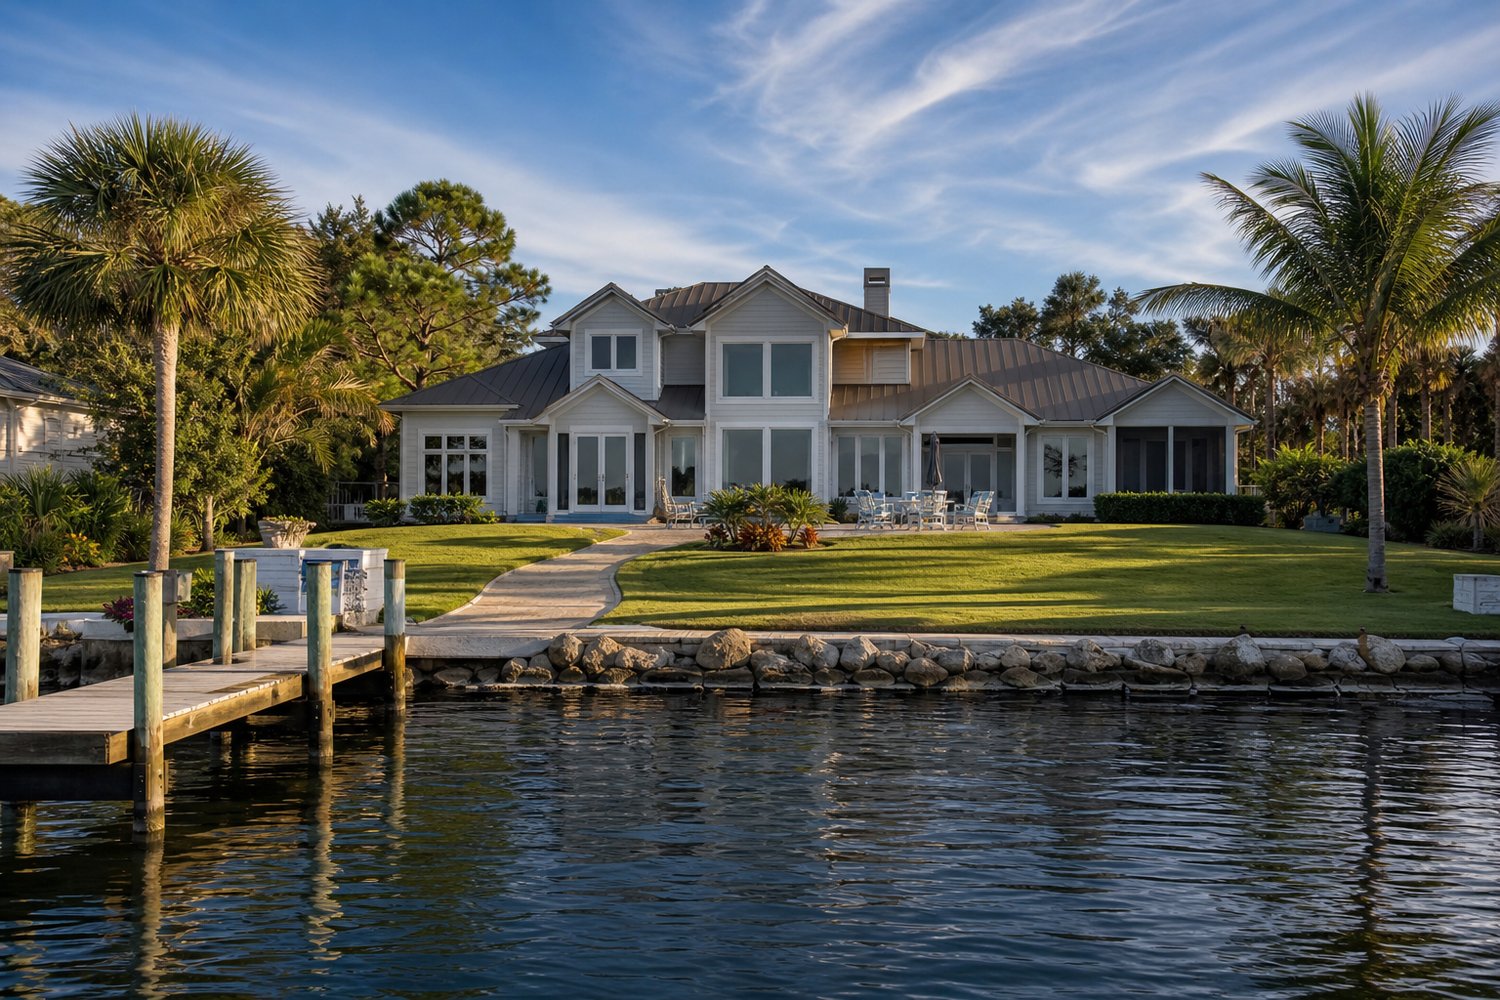
Before you fall for the view, decide how you'll use the house. Then verify three things on the parcel itself: which government has jurisdiction, what the flood map says, and who will look after the property while you're away. Those answers shape your insurance, your rental options, and your real cost of owning.
Ocean View Isn't Enough for a Flagler Beach Second Home
Is an ocean view enough to justify a second home in Flagler Beach?
No. The ocean view sells the house, but your intended use, the flood exposure, the insurance, and the upkeep decide whether it works as a second home. Before you make an offer, confirm which government has jurisdiction over the parcel, what the FEMA flood map says about it, and who will handle the property when you're not there.
Key Takeaways
- Recent local market data shows a median sale price of $520,000 for Flagler Beach homes sold over the trailing 90 days, and that is an area-level figure, not a prediction for any one house.
- Homes for sale now number 148 in Flagler Beach, with 33 new listings in the last 30 days, so you have room to compare properties instead of settling for the first view you like.
- Standard homeowners insurance does not cover flood damage, and Flagler County notes a 30-day waiting period before a National Flood Insurance Program policy takes effect.
- In unincorporated Flagler County, a short-term rental certificate is not transferable to a new owner, so a property's rental history is something you verify, not something you inherit.
Is an ocean view worth paying for in a Flagler Beach second home?
It can be, but treat the ocean view as one feature on a list, not the whole case. I've watched buyers step onto a porch, see the Atlantic, and stop asking questions. The questions you skip in that moment are the ones that cost you later.
What does the Flagler Beach market look like right now?
Recent local market data for single homes and condos combined is not broken out here, so read these as area-level figures: the median sale price for Flagler Beach homes sold over the trailing 90 days was $520,000, with 59 homes sold in that window. There are 148 homes for sale now, and 33 of them were new listings in the last 30 days.
That tells you there is real selection. It does not tell you what a specific house is worth, because condition, street, build year, and timing move the number. For the bigger picture, I broke down the Flagler Beach real estate market for 2026 in a separate post.
What should you weigh against the view?
Here's the list I run with every second-home buyer before we talk price:
- Upkeep: who handles the yard, the exterior, any pool, and the surprises that show up when nobody is home.
- Access: how easy it is to reach the house, park at it, and get in and out when you arrive with a car full of luggage.
- Insurance: what a flood policy and your other coverage will require for this exact address.
- Intended use: whether the rules allow what you actually plan to do with the house.
- Time: how many weeks a year you'll realistically be there, because a house you use rarely needs a stronger plan than one you use often.
Your numbers on each of these depend on the property and on how you live. This is exactly the kind of math I work through with my clients before we write an offer.
How does your intended use change which Flagler Beach home you should buy?
Your plan for the house decides what you need to verify, because rental and occupancy rules depend on the jurisdiction, the zoning, and the type of building. A buyer planning a few personal weeks a year has a very different checklist from a buyer who wants nightly rental income.
Who sets the rules for your parcel?
Jurisdiction comes first. A Flagler Beach address is governed by the City of Flagler Beach. An address elsewhere in the county may be in Palm Coast or in unincorporated Flagler County, and each can have its own rules on zoning, permitting, and inspections. If your search stretches across Flagler Beach, Cinnamon Beach, and the Hammock communities, check the governing authority parcel by parcel instead of assuming one rulebook.
| How you plan to use it | What to verify before you offer | Who to ask |
|---|---|---|
| Occasional personal use | Flood zone, insurance requirements, HOA or condo rules on occupancy and access | Insurer, association, your REALTOR® |
| Seasonal personal use | Owner-away plan, storm readiness, utilities and upkeep arrangements | Local property caretaker, insurer |
| Long-term lease | Zoning, association rules on leasing, lender and insurance terms | City or county, association, lender |
| Nightly vacation rental | Jurisdiction, certificate history, parking capacity, building type, association documents | City or county staff, association, your REALTOR® |
Can you use a Flagler Beach house as a short-term vacation rental?
Maybe, but you confirm it before you buy, not after. In unincorporated Flagler County, the county's short-term vacation rental certificate application says an owner needs an annual certificate for each dwelling unit before renting it, unless an exception in the county code applies. The same document says the certificate is not transferable, so after a sale the new owner must obtain a transfer certificate.
The county application also says the ordinance does not apply to certain multifamily buildings, areas west of U.S. Highway 1, and qualifying owner-occupied properties. That's why I never tell a buyer "it's already a rental, so you're set." Existing rental status is not an automatic right that comes with the deed.
Inside the city limits, the picture is still moving. A Flagler Beach staff report describes proposed amendments to the city's land-development regulations covering rental units and fire-inspection procedures for resort dwellings and resort condominiums. It describes a section that would apply to dwelling-unit rentals within the city but not to hotels, motels, resorts, long-term rentals, or bed-and-breakfast inns. I can't tell you from a blog post what the final operative text says for your address, so get the current city code and a zoning determination in writing before you count on rental income.
Do parking and occupancy limits matter?
They matter more than most buyers expect. The county application requires at least one off-street parking space per three occupants, and it says street and yard parking are not allowed for the rental. A beautiful house with a one-car driveway may simply not support the guest count you had in mind. Occupancy under the certificate is also controlled by the certificate itself, and condo or HOA documents can add their own limits.
What do you need to know about flood zones and insurance before closing?
Check the specific parcel's FEMA flood designation and your insurance options before you commit, because standard homeowners insurance does not cover flood damage. Flagler County says that coverage is available through the National Flood Insurance Program, and that a 30-day waiting period applies before a policy takes effect, subject to policy-specific exceptions.
Is flood insurance required if you buy without a mortgage?
The county's stated requirement is tied to financing. Flagler County says homes carrying a mortgage in a high-risk flood zone must have flood insurance. If you're paying cash, no lender is imposing that rule, but the exposure is still yours, because a standard homeowners policy won't pay for flood damage. Confirm what applies to you with your insurer and, if you're financing, your lender.
How do you check the flood risk on one specific house?
Don't rely on the listing description, and don't assume the house next door tells you anything. The county points owners to official FEMA Flood Insurance Rate Maps and notes that flood risk can differ substantially between nearby properties. For each home on your shortlist, I'd look at:
- The mapped FEMA flood zone designation for that parcel
- Elevation information, where it's available
- Any prior flood or storm damage, and the drainage history
- Roof and opening protection on the building
- The insurer's underwriting requirements for that address
Because of the 30-day wait, I tell buyers to start insurance conversations well ahead of closing and well ahead of storm season, not when a forecast cone shows up. Policy availability, exclusions, and deductibles vary, so get quotes from an insurer for the exact address. I can't give you a premium estimate here, and nobody honest can without the property in front of them.
Who looks after a Flagler Beach second home when you're not there?
You need a named local person or company and a written plan, because storms and water intrusion don't wait for your flight. This is where second homes succeed or fail, and it has little to do with the view.
Flagler County's Emergency Management department publishes resources on flood-zone risk, flood safety, property protection, and insurance. Read them as an owner who may be hundreds of miles away when a storm threatens. Your owner-away plan should answer these questions in writing:
- Who monitors the property during a storm watch and after?
- Who secures outdoor items such as furniture, grills, and decor?
- Who responds to water intrusion and has access to the house?
- Who coordinates repairs and gets contractors scheduled?
- Who documents damage for your insurer, and how do you receive those photos?
I haven't included cost ranges for storm prep, pool care, landscaping, or property management, because those should come from current local vendor quotes, not from a national average. When we work together, I help you build this list before you ever write an offer, so the plan is in place on closing day. Your closing agent handles the closing and settlement itself, but the owner-away system is yours to design, and I'd rather you design it early.
If you want to see what past clients say about working with me, you can read my reviews on Google and Zillow.
FAQ
Can I use a Flagler Beach house as a short-term vacation rental?
It depends on the jurisdiction, zoning, and building type, so verify before you offer. Flagler Beach is governed by the city, which has been working on rental-unit rule changes, while unincorporated Flagler County uses an annual certificate for many short-term rentals. Palm Coast and unincorporated areas are not governed by the same rules as the city, so confirm the authority for your specific parcel and get the current code in writing.
Is flood insurance required if I buy the property without a mortgage?
The county's stated requirement applies to mortgaged homes in a high-risk flood zone, so a cash buyer isn't bound by a lender's rule. Even so, standard homeowners insurance does not cover flood damage, so you'd carry that risk yourself without a separate policy. Talk to an insurer about the exact address before closing.
How long does flood insurance take to become effective in Flagler County?
Flagler County notes a 30-day waiting period before flood insurance takes effect, subject to policy-specific exceptions. That means you should arrange coverage well before closing and well before storm season, not once a storm is in the forecast. Your insurer or lender can confirm how the waiting period applies to your policy.
What happens to a vacation-rental certificate when a Flagler County property is sold?
For covered unincorporated-county rentals, the certificate is not transferable between owners, and the new owner must obtain a transfer certificate. The county application also sets occupancy through the certificate and requires at least one off-street parking space per three occupants. Confirm the property's certificate history with the county before you count on rental income.
What should I arrange locally if I will leave my second home vacant during hurricane season?
Arrange a local contact who can monitor the house, secure outdoor items, respond to water intrusion, coordinate repairs, and document damage for your insurer. Put it in writing before you need it, and review the resources Flagler County Emergency Management provides for property owners. I walk my buyers through this plan before they make an offer.
Ready to look past the view?
An ocean view is where a Flagler Beach second-home search starts, not where it ends. The use rules, flood exposure, insurance timing, and owner-away plan are what make the house work for you year after year. If you'd like to run those questions against specific properties, schedule a consultation with me or call 304-382-3006, and we'll build your checklist before you fall for a porch.
Equal Housing Opportunity. M. Gina DosSantos, Broker Associate, Coastal Gateway Real Estate Group. This article is general information, not legal, tax, or financial advice. Confirm your own numbers and requirements with your closing agent, tax advisor, insurer, or lender.
Categories
Recent Posts